


Advertisement
Advertisement
I know someone who will walk two extra blocks for noodles that are 50 cents cheaper, and who only goes to town when a buddy can give him a ride.
Yet a few years back, this same person paid the highest price for their four-room flat in the area they live in.
Next year, this individual plans to upgrade to a five-room flat that is closer to their office.
It’s not a huge difference in travel time — perhaps just around three stops closer by train.
So what does this have to do with the recently concluded June 2026 BTO flat applications and HDB resale prices?
I think there’s a fair bit to take away from my acquaintance’s mindset and the demand for new BTO flats in the latest sales exercise.
We reported that the sales exercise drew over 22,3 applications for 6,952 flats, which we covered in this article here.
We saw that two Prime projects — Berlayar Rise and Lakeview Cascadia — accounted for around 65per cent of all applications. Meanwhile, the two Standard projects in Sembawang were undersubscribed among first-timer families.
These weren’t typical Standard BTO projects — they came with a shorter build time of under three-years. However, application rates were just 0.7 for three-room flats, 0.6 for four-room flats and 0.4 for five-room flats.
Regardless, most of the interest among BTO applicants went toward the Plus and Prime flats.
These are pricier, will take longer to build, and come with restrictions that go way beyond a 10-year MOP.
But the high application rates indicate that most BTO owners are willing to accept that, along with the heftier price tag.
Let’s consider the new four-room BTO flats. Buyers could have applied for a four-room flat at Sembawang Brook that would be priced from $302,000, or at Woodgrove Acres that starts from $353,000.
Instead, we saw that a relatively large proportion of the demand flowed toward Lakeview Cascadia, where four-room flats start from $534,000, and Kebun Baru Ridge where these units are priced from $543,000, as well as Berlayar Rise which sees prices from $592,000.
(For a thorough review of all the projects in this sales exercise, see our June BTO launch guide).
That’s a premium of roughly $180,000 to almost $300,000 before grants.
Yet these projects still attracted the lion’s share of applications, despite longer waiting times and significantly tighter resale restrictions.
This is in stark contrast with some Singaporeans who I have met over the years.
Most are eminently practical and willing to go far to preserve their savings, but when it comes to housing — just as with their children’s education apparently — the restraints loosen.
It appears that these same reasons drive the behaviour of my acquaintance.
When it comes to housing, affordability matters. But that’s not the same as simply going for the cheapest option; it’s about looking for the biggest improvement that they can realistically afford.
But is this just about resale value and upgrading to a condo?
I’m not entirely sure. I acknowledge the possibility that some Singaporeans have underestimated the impact of Prime and Plus restrictions.
As I pointed out previously, many buyers seem to focus on just the 10-year MOP and Subsidy Recovery.
I notice fewer buyers focus on the resale income ceiling and Mortgage Servicing Ratio (MSR), which will also apply to future buyers.
Along with the Subsidy Recovery and almost 13-year total wait time, Plus and Prime projects have built-in mechanisms that dissuade windfall seeking owners.
That said, I think it’s more likely that most buyers at least understand the broad trade-offs.
Some may be underestimating the degree of the effect, but in general they know they’re accepting significant drawbacks.
And yet, many have consciously decided the trade-offs are worth the while.
Their day-to-day quality of life, from being in a more convenient location, may come ahead of resale gain or property progression.
If so, this may also explain the stubborn refusal of resale flat prices to fall
If Singaporeans value location, convenience, and quality of life above room for price growth, upgrading, etc., then it also explains why it’s so hard for resale flat prices to dip — even if there’s higher supply in the market.
Over the past year, the HDB resale market has seen much more supply. Around 13,480 flats are expected to reach their MOP this year, almost double last year’s 6,973 units.
The public housing market has also improved since the end of the Covid-19 pandemic.
We went from a scene where new housing supply couldn’t keep up with demand, to a situation where the overall supply has matched long-term demand trends.
And yet in the first three months of this year, about a third of resale buyers still paid at least $800,000 for their flats, and million-dollar transactions continue to climb.
The broader resale market may be cooling, but demand for the most desirable locations remains unshakeable.
The overwhelming demand for Plus and Prime flats may simply be another expression of the same mindset we already see in the resale market.
When given a choice, many Singaporeans will pay a substantial premium for a home that better suits them.
If a million-dollar resale price ever follows, that’s welcome. But perhaps for an increasing number of buyers, that’s a secondary benefit.
It would also explain why the negative impact of lease decay keeps getting shrugged off.
In our analysis last year, we found that many 50-year-old flats in mature estates continued to sustain high prices.
Older five-room flats in Toa Payoh still saw average prices of above $1 million in 2025, while similarly aged units in Marine Parade recorded average prices of around $938,000, and Kallang/Whampoa around $765,000.
Even four-room flats in Queenstown, Marine Parade and Bukit Timah continued to transact comfortably above the $600,000 mark.
If a substantial number of Singaporeans aren’t even afraid of lease decay, despite the end of Sers, then a 10-year MOP, Subsidy Recovery, and income ceiling scare them even less.
Whether this was the government’s intention or not, it seems to me that the introduction of Plus and Prime flats may have ended up doing more than just preventing unfair windfalls.
It created a system that reveals a big part of the Singaporean homeowner’s psyche towards home ownership.
These rules deliberately make these flats less attractive to buyers chasing gains, yet we find many Singaporeans still rushing for them.
At the same time, we can see on the tail-end that prices of central area flats — in their last 50 years of existence — defy gravity and continue to draw interested buyers.
Put the two together, and it contours a very common online complaint: that Singaporeans keep using HDB flats as investment assets. In reality, all the behaviour so far points in the opposite direction.
Resale flat prices are expensive precisely because most Singaporeans prize home ownership over yield, capital gain, or other spreadsheet calculations.
Persistently high resale prices may not simply suggest that Singaporeans treat public housing as investment assets.
It may reflect something much more mundane: We’re willing to pay a premium to live where we genuinely want to live.
And we’re willing to do so regardless of Plus and Prime restrictions, or lease decay.
Weekly sales roundup (June 15 – 21)
Top 5 most expensive new sales (by project)
Project name | Price S$ | Area (sqft) | $PSF | Tenure |
River Modern | $6,180,000 | 1830 | $3,377 | 99 years (2025) |
One Marina Gardens | $5,418,000 | 1647 | $3,290 | 99 years (2023) |
The Continuum | $5,330,000 | 1905 | $2,798 | FH |
J’den | $3,751,000 | 1485 | $2,525 | 99 yrs |
Canninghill Piers | $3,613,000 | 1130 | $3,197 | 99 yrs (2021) |
Top 5 cheapest new sales (by project)
Project name | Price S$ | Area (sqft) | $PSF | Tenure |
Narra Residence | $1,542,000 | 700 | $2,204 | 99 years (2025) |
Coastal Cabana | $1,670,000 | 915 | $1,825 | 99 years (2024) |
Bloomsbury Residences | $1,720,000 | 678 | $2,536 | 99 years (2024) |
Hudson Place Residences | $1,765,000 | 689 | $2,562 | 99 years (2025) |
Canberra Crescent Residences | $1,995,861 | 990 | $2,015 | 99 years (2024) |
Top 5 most expensive resale
Project name | Price S$ | Area (sqft) | $PSF | Tenure |
Hilltops | $8,088,600 | 2379 | $3,400 | FH |
Draycott Eight | $7,500,000 | 2906 | $2,581 | 99 years (1997) |
The Draycott | $5,650,000 | 2637 | $2,142 | FH |
Palm Spring | $4,360,000 | 1862 | $2,341 | FH |
Leonie Gardens | $4,200,000 | 2540 | $1,653 | 99 years (1990) |
Top 5 cheapest resale
Project name | Price S$ | Area (sqft) | $PSF | Tenure |
River Isles | $720,000 | 441 | $1,631 | 99 years (2012) |
Skysuites17 | $735,000 | 377 | $1,951 | FH |
EuHabitat | $755,000 | 538 | $1,403 | 99 years (2010) |
Space @ Kovan | $783,666 | 549 | $1,428 | FH |
Treescape | $793,000 | 431 | $1,842 | FH |
Top 5 biggest winners
Project name | Price S$ | Area (sqft) | $PSF | Returns | Holding period |
Leonie Gardens | $4,200,000 | 2540 | $1,653 | $2,930,000 | 28 Years |
The Esta | $3,388,888 | 1346 | $2,519 | $2,464,278 | 20 Years |
Mirage Tower | $3,700,188 | 1496 | $2,473 | $2,370,188 | 20 Years |
Blossoms @ Woodleigh | $2,768,000 | 1206 | $2,296 | $1,993,000 | 19 Years |
Gold Coast Condominium | $3,200,000 | 1894 | $1,689 | $1,800,000 | 17 Years |
Top 5 biggest losers
Project name | Price S$ | Area (sqft) | $PSF | Returns | Holding period |
Marina Collection | $2,780,000 | 1873 | $1,484 | -$2,167,760 | 18 Years |
Reflections at Keppel Bay | $4,050,000 | 2336 | $1,734 | -$782,100 | 19 Years |
Robinson Suites | $1,155,000 | 506 | $2,283 | -$565,000 | 16 Years |
OUE Twin Peaks | $1,175,000 | 570 | $2,060 | -$394,100 | 10 Years |
Marine One Residences | $1,270,000 | 753 | $1,686 | -$347,145 | Six Years |
Top 5 biggest winners (ROI per cent)
Project name | Price S$ | Area (sqft) | $PSF | ROI (per cent) | Holding period |
Braddell View | $1,541,688 | 1453 | $1,061 | 267per cent | 20 Years |
The Esta | $3,388,888 | 1346 | $2,519 | 267per cent | 20 Years |
Blossoms @ Woodleigh | $2,768,000 | 1206 | $2,296 | 257per cent | 19 Years |
Leonie Gardens | $4,200,000 | 2540 | $1,653 | 231per cent | 28 Years |
The Tessarina | $2,400,000 | 1033 | $2,323 | 216per cent | 22 Years |
Top 5 biggest losers (ROI per cent)
Project name | Price S$ | Area (sqft) | $PSF | ROI (per cent) | Holding period |
Marina Collection | $2,780,000 | 1873 | $1,484 | -44per cent | 18 Years |
Robinson Suites | $1,155,000 | 506 | $2,283 | -33per cent | 16 Years |
OUE Twin Peaks | $1,175,000 | 570 | $2,060 | -25per cent | 10 Years |
Marina One Residences | $1,270,000 | 753 | $1,686 | -22per cent | Six Years |
Reflections at Keppel Bay | $4,050,000 | 2336 | $1,734 | -16per cent | 19 Years |
Transaction breakdown
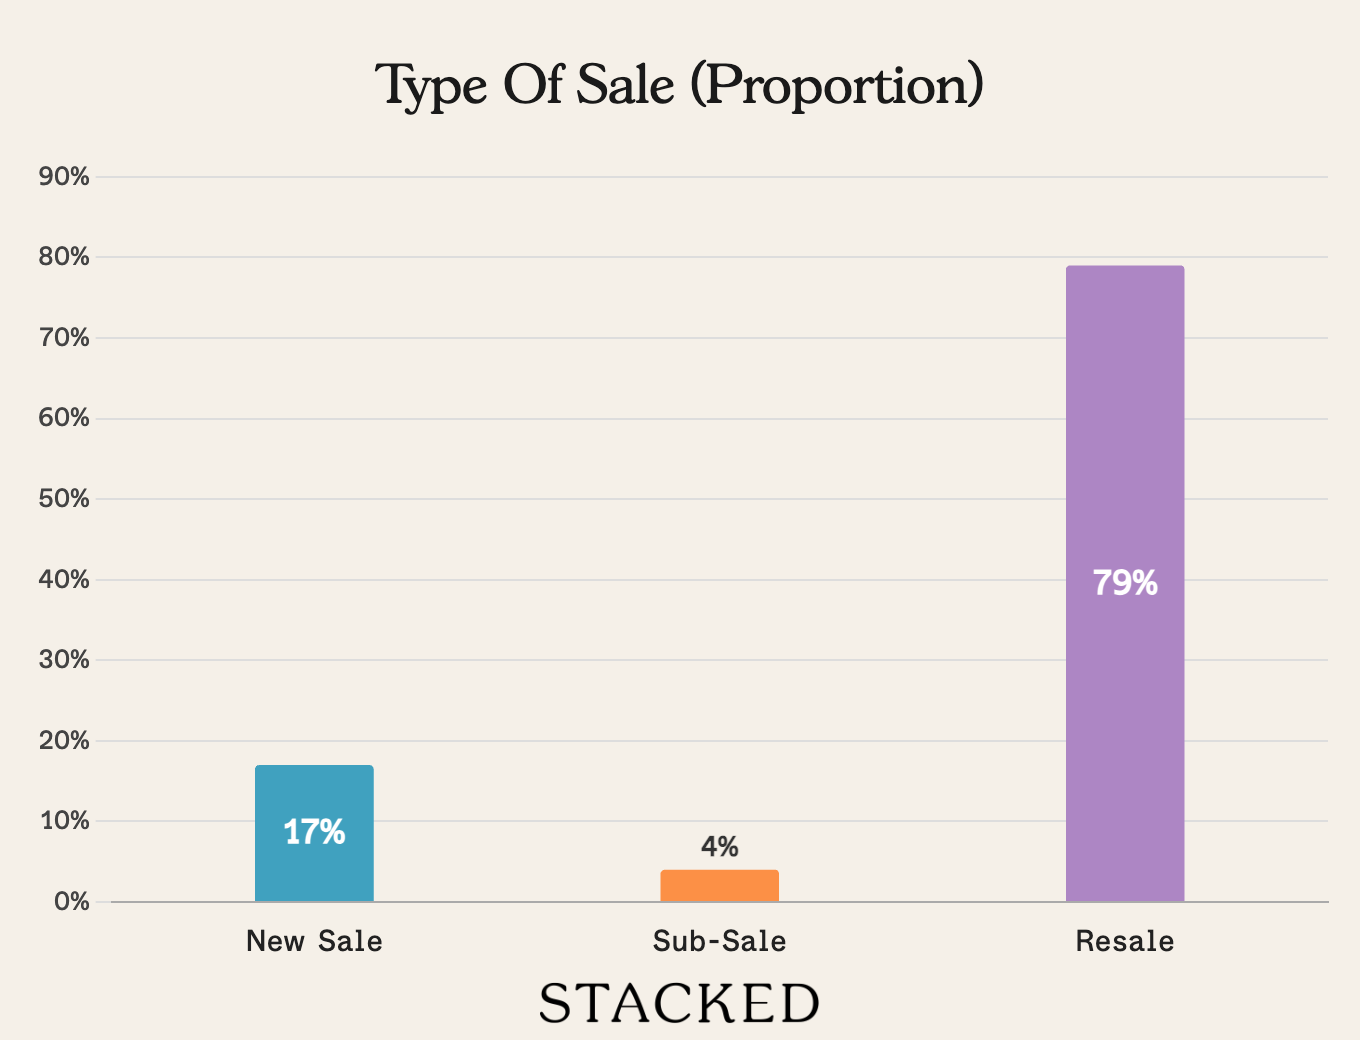
PHOTO: Stackedhomes
This article was first published in Stackedhomes.
Advertisement
Advertisement


Advertisement


